A cancer diagnosis can affect much more than your health. It may also create unexpected medical bills, time away from work, transportation expenses, and pressure on your household budget. Understanding the difference between cancer insurance and health insurance can help you prepare for these financial challenges.
The main difference is that health insurance helps pay for covered medical care for many illnesses and injuries, while cancer insurance provides additional benefits specifically when a covered cancer-related event occurs. Depending on the policy, cancer insurance may pay a lump sum or fixed benefits that can help with eligible treatment expenses and other financial needs.
For individuals and families in Florida, choosing the right coverage means looking beyond monthly premiums. You need to understand what each policy pays, what it excludes, and how the two types of insurance may work together.
In this guide, we explain cancer insurance vs health insurance, compare their benefits, and outline what to consider before purchasing either policy.
What Is the Difference Between Cancer Insurance and Health Insurance?
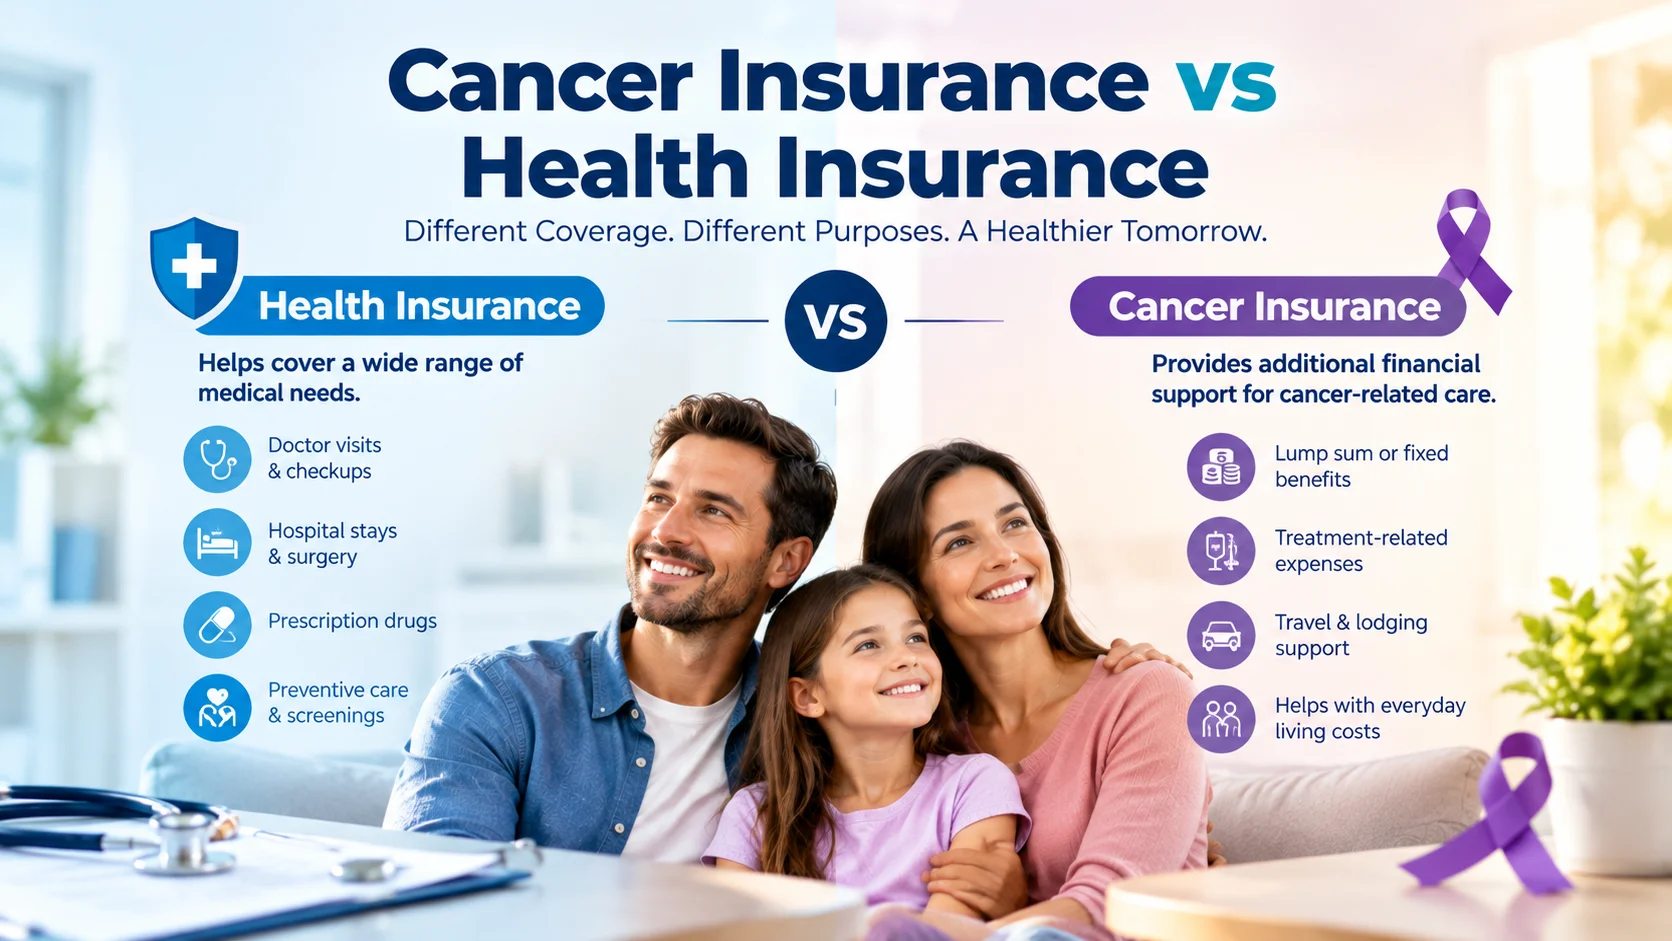
Health insurance is designed to help cover eligible medical services for a wide range of conditions. Cancer insurance is a supplemental policy that provides specified benefits related to a covered cancer diagnosis or treatment.
Here is a quick comparison:
| Feature | Health Insurance | Cancer Insurance |
| Main purpose | Covers eligible medical care for many health conditions | Provides specified benefits related to covered cancer events |
| Coverage scope | Broad medical coverage | Cancer-specific coverage |
| Doctor visits | Covered according to plan terms | May pay specified benefits for eligible visits or services |
| Cancer treatment | May cover eligible chemotherapy, radiation, surgery, and other care | May pay fixed benefits for covered cancer-related events |
| Other illnesses | Covers many other eligible conditions | Generally does not provide benefits for unrelated illnesses |
| Payment method | Usually pays providers or reimburses covered expenses under plan terms | May pay fixed benefits to you or another designated recipient, depending on the policy |
| Role | Primary medical coverage | Supplemental financial protection |
| Best use | Managing healthcare costs across many conditions | Adding financial support for covered cancer-related expenses |
Actual benefits vary by insurer and policy. Review the contract to understand coverage limits, waiting periods, exclusions, and payment rules.
The National Association of Insurance Commissioners (NAIC) explains that health insurance generally helps pay for services such as doctor visits, hospital stays, prescriptions, and other covered healthcare needs. Cancer insurance is a more limited type of specified-disease coverage.
How Does Health Insurance Cover Cancer Treatment?
Health insurance is usually your first line of financial protection when you need cancer care. Depending on your plan, it may cover eligible diagnostic tests, specialist consultations, surgery, chemotherapy, radiation therapy, prescription drugs, and hospital services.
However, coverage does not always mean that every bill is paid in full.
Your share of the cost may depend on your deductible, copayments, coinsurance, provider network, and annual out-of-pocket maximum. Certain services may also require prior authorization or meet medical-necessity requirements.
What cancer-related services may health insurance cover?
Depending on the policy and medical circumstances, coverage may include:
- Consultations with oncologists and other specialists.
- Diagnostic tests and medically necessary imaging.
- Covered cancer surgeries and hospital services.
- Eligible chemotherapy and radiation treatments.
- Prescription medications included in the plan’s benefits.
- Follow-up appointments and certain rehabilitation services.
Preventive coverage is another important consideration. Many health plans cover specified preventive cancer screenings without cost-sharing when eligibility and plan rules are met. Diagnostic testing after symptoms appear may be treated differently from preventive screening.
What might you still have to pay?
Even with health insurance, you could be responsible for:
- Your deductible before certain benefits begin.
- Copayments and coinsurance for covered services.
- Costs for services that are not covered.
- Certain out-of-network expenses.
- Nonmedical costs such as travel, parking, meals, and household assistance.
For example: imagine you have a health plan with a $2,000 deductible and 20% coinsurance for a particular covered service after the deductible. You may need to pay the deductible first and then your applicable share of eligible costs, subject to the plan’s rules and out-of-pocket limit.
This is why comparing health insurance plans based only on their monthly premiums can be misleading. HealthCare.gov recommends evaluating total estimated annual costs, including premiums, deductibles, copayments, and coinsurance.
If you are reviewing your coverage options, explore our guide to health insurance options for Florida families to learn more about comparing medical coverage and household costs.
What Is Cancer Insurance and How Does It Work?
Cancer insurance is supplemental coverage designed to provide specified benefits when you experience a covered cancer-related event.
Unlike comprehensive health insurance, it generally does not cover your full range of medical needs. Instead, the policy may pay a defined amount for an eligible diagnosis, treatment, hospital stay, or other covered event.
Some policies pay a lump sum after a qualifying diagnosis. Others pay fixed amounts for specified services or periods of care. The payment structure depends on the policy.
What can cancer insurance benefits pay for?
Depending on the terms of your policy, benefits may help with expenses such as:
- Deductibles and coinsurance.
- Certain cancer-related treatment expenses.
- Transportation to appointments.
- Lodging when treatment requires travel.
- Childcare or household assistance.
- Everyday bills while you are away from work.
These are possible uses of benefits, not guaranteed payments. Whether an expense qualifies depends on how the policy pays benefits and any applicable restrictions.
For example, a policy that pays a lump sum may give you more flexibility than one that pays fixed amounts only for listed services. However, the premium, benefit limits, qualifying conditions, and exclusions should all be considered.
Can cancer insurance cover an existing cancer diagnosis?
Usually, you should not expect a new cancer insurance policy to pay benefits for a cancer diagnosis that existed before coverage began. Policies commonly have pre-existing-condition exclusions and may also include waiting periods or other eligibility requirements.
Read the policy carefully before applying. If you have already received a diagnosis, ask the insurer to explain the eligibility rules in writing.
Cancer insurance should generally be considered before a diagnosis as part of a broader financial protection strategy, not as a way to pay for treatment that is already underway.
Cancer Insurance vs Health Insurance: Which Is Better?
For most people, comprehensive health insurance is the most important starting point because it can cover a wide range of eligible healthcare needs, including cancer treatment.
Cancer insurance may provide additional financial support, but it is not a replacement for major medical coverage.
The right decision depends on your existing insurance, savings, budget, and the specific terms of any supplemental policy you are considering.
When health insurance may be your priority
Focus on securing appropriate health insurance if you:
- Do not currently have comprehensive medical coverage.
- Need coverage for routine care and a broad range of illnesses.
- I want access to eligible specialist care and prescription benefits.
- Need to compare deductibles, provider networks, and out-of-pocket limits.
If you live in Florida and need individual or family coverage, compare available options and check whether you qualify for Marketplace financial assistance.
When cancer insurance may be worth considering
A supplemental cancer policy may be worth evaluating if you already have health insurance and:
- Want additional benefits for specified cancer-related events.
- Are concerned about expenses that your savings may not comfortably cover.
- I want to understand whether fixed cash benefits could help with household costs.
- Have compared the premium against the policy’s actual benefits and limitations.
It is important not to assume that having two policies means every expense will be paid twice. The way benefits are coordinated and the type of cancer policy you choose can affect what you receive.
A Real-World Example: How the Two Policies May Work Together
Consider a hypothetical Florida family with a comprehensive health insurance plan and a supplemental cancer insurance policy.
One parent receives a qualifying cancer diagnosis and needs surgery followed by several months of treatment.
The health insurance plan processes eligible medical claims according to its terms. It may pay covered costs after the applicable deductible and cost-sharing requirements are met.
The family may still face out-of-pocket expenses and nonmedical costs. The parent may need time away from work, while the family may pay for travel to appointments or help with childcare.
If the supplemental cancer policy covers the diagnosis or treatment, it may provide the specified benefit. Depending on the contract, the money may help the family manage some of these additional expenses.
This example illustrates the different roles of the policies. It does not guarantee a particular payment or amount. Actual benefits depend on the plan documents, eligibility rules, and circumstances of the claim.
How to Choose Between Cancer Insurance and Health Insurance?
Before buying a policy, review your current coverage and identify where you may have financial gaps.
1. Review your existing health insurance
Check your deductible, coinsurance, out-of-pocket maximum, prescription coverage, and specialist network. Confirm whether the hospitals and cancer treatment providers you would consider are in-network.
2. Estimate the financial gap
Think about more than medical bills. Consider emergency savings, monthly household expenses, potential income loss, travel, and caregiving needs.
You do not need to predict every future expense. The goal is to understand how much financial pressure your household could manage if treatment disrupted your normal routine.
3. Compare cancer policy benefits
Ask whether the policy pays a lump sum or fixed benefits. Check the qualifying diagnosis requirements, covered treatments, maximum benefit amounts, waiting periods, renewability, and exclusions.
Also ask whether the policy covers different cancer types and stages, and whether benefits are reduced or limited for particular circumstances.
4. Compare the total cost
Add the cancer insurance premium to your existing insurance costs. Consider whether the extra coverage offers meaningful value compared with building emergency savings or addressing gaps in your primary medical coverage.
5. Ask questions before enrolling
Request clear answers about how claims work, when benefits begin, whether you can keep the policy if you change jobs, and how benefits may interact with other coverage.
For additional guidance, L. Thomas Insurance can help you review your insurance needs and understand the questions to ask when comparing coverage options in Florida. Start with our insurance coverage review checklist to identify potential gaps in your existing protection.
Is Cancer Insurance Worth It for Florida Residents?
Cancer insurance may be useful for some Florida residents, but it is not necessary or suitable for everyone.
Its value depends on your primary health coverage, financial reserves, risk tolerance, premium, and the policy’s actual benefits. A plan with a low premium may also have restrictive eligibility rules or limited payouts. A more expensive policy is not automatically better.
Before buying supplemental cancer insurance, make sure you have considered comprehensive medical coverage first. Then evaluate whether the additional policy addresses a genuine financial concern.
If you are approaching retirement or already enrolled in Medicare, review your existing coverage carefully before purchasing a cancer policy. Medicare, Medicare Advantage, Medicare Supplement, and prescription drug coverage have different rules and costs. A cancer policy may not address the coverage gap you are most concerned about.
You can learn more about available options in our guide to Medicare plans in Florida.
L. Thomas Insurance encourages consumers to compare policy details rather than choosing coverage based on advertising alone. Understanding the benefits and limitations before enrollment can help you make a more informed decision.
Final Thoughts
When comparing cancer insurance vs health insurance, remember that the two policies serve different purposes. Health insurance is designed to help pay for eligible medical care across many conditions. Cancer insurance may provide additional financial benefits when a covered cancer event occurs.
For most households, securing suitable comprehensive health insurance should come first. After reviewing your existing coverage and savings, you can decide whether supplemental cancer insurance fits your needs and budget.
If you live in Florida and want help reviewing your options, contact L. Thomas Insurance to discuss your insurance needs and the questions to ask before choosing a policy. Compare the details carefully, understand the exclusions, and choose coverage based on your circumstances rather than fear.
Frequently Asked Questions
1. Is cancer insurance the same as health insurance?
No. Health insurance provides coverage for a broad range of eligible medical services. Cancer insurance is supplemental coverage that pays specified benefits for qualifying cancer-related events. Cancer insurance should not replace comprehensive health insurance.
2. Does health insurance cover chemotherapy and radiation?
Many comprehensive health insurance plans cover medically necessary chemotherapy and radiation when the services meet plan requirements. Your costs depend on your policy, provider network, deductible, coinsurance, and any applicable authorization rules. Check your plan documents before treatment.
3. Can I have cancer insurance and health insurance at the same time?
Yes. Eligible consumers may hold both types of coverage. Health insurance generally handles covered medical claims, while cancer insurance may pay additional benefits for qualifying events. The exact payments and restrictions depend on both contracts.
4. Should I buy cancer insurance if I already have health insurance?
It depends on your financial situation and the policy. Review your current medical coverage, savings, potential out-of-pocket costs, and the cancer policy’s premium and benefit limits. Supplemental coverage may be helpful for some households, but it may offer limited value to others.
Disclaimer: Insurance benefits, eligibility, premiums, exclusions, and availability vary by policy and insurer. This article is for general educational purposes and is not medical, legal, or financial advice. Review the actual policy documents and consult an appropriately licensed insurance professional for guidance on your situation.
Also Read: Life Insurance in Florida